

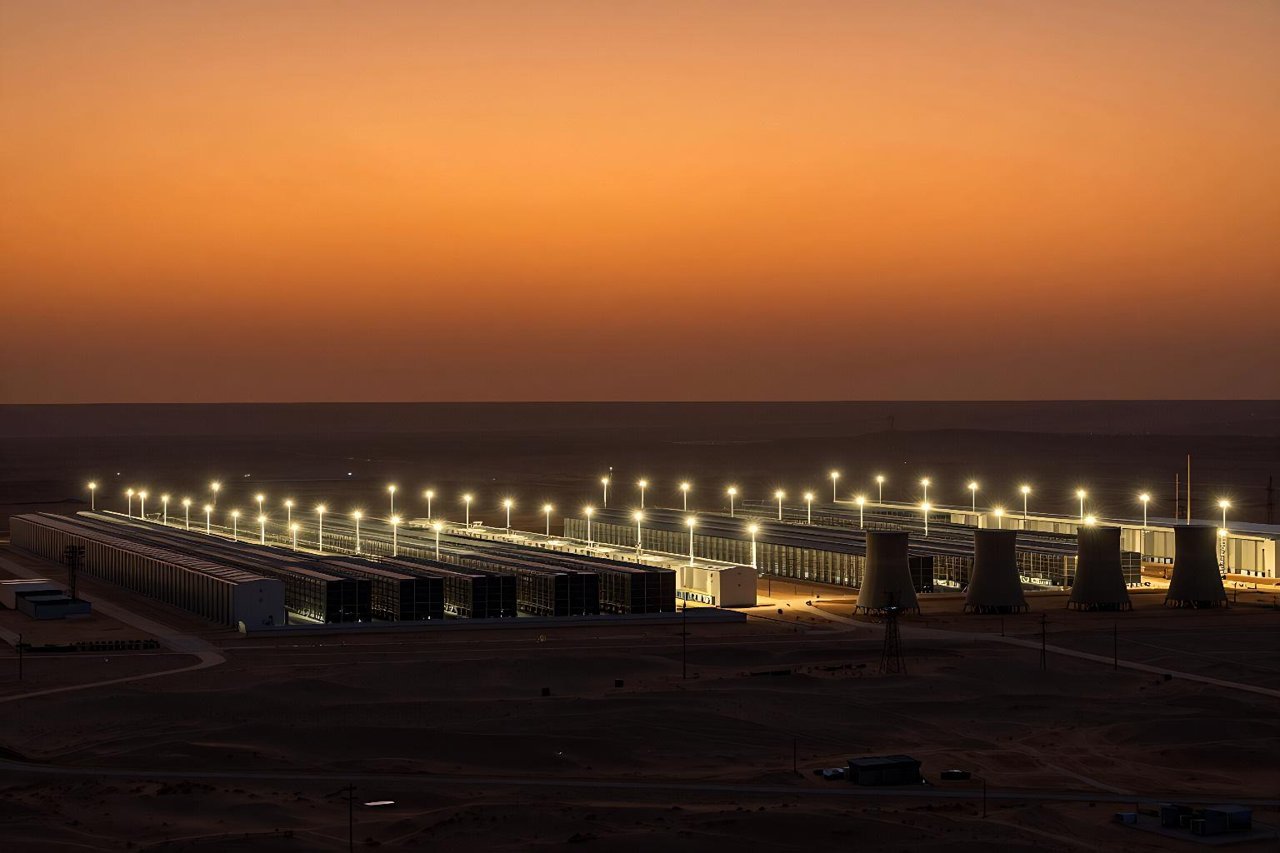
A single frontier training run now costs more than the entire annual research budget of a mid-sized university. That one fact explains most of what feels strange about AGI research funding: the sums are enormous, the spending is concentrated in a handful of buildings in California and London, and the distance between a press release and a working system keeps getting harder to judge.
It helps to be precise about the target before arguing about the money. “AGI” still resists a clean definition, and the plain-English explanation of what AGI actually means is a reasonable starting point. Once you accept that the goal is fuzzy, the funding picture gets easier to read: most of the money isn’t buying a finished destination, it’s buying the infrastructure to keep searching.
The Numbers Are Real, and Mostly Capital Expenditure
Headline funding rounds get the attention, but the bigger story sits in corporate capex lines. Microsoft, Alphabet, Amazon and Meta have between them committed well over $300 billion in a single year to data centres, accelerators and power contracts. Nvidia’s data centre revenue alone now dwarfs the total research budgets of every national AI institute on earth combined.
That spending isn’t research funding in the traditional sense. It’s the cost of admission. You cannot run a serious AGI research programme in 2026 without a cluster of tens of thousands of accelerators, and you cannot rent one cheaply. When a lab says it is “investing in fundamental research,” a large share of that number is really a facilities bill.
Who Actually Writes the Cheques
Hyperscalers, funding from the balance sheet
Google DeepMind, Microsoft Research and Meta’s FAIR group are unusual in the history of science: they are funded by profitable parent companies rather than grants. That buys speed and tolerance for long horizons, but it also means research priorities track product roadmaps. A promising line of inquiry that doesn’t map to a shippable feature tends to lose its headcount quietly.
Venture capital, with a concentration problem
Private rounds for the leading labs have reached the tens of billions, at valuations that would have seemed absurd a few years ago. The money is real, but it is extraordinarily concentrated. A handful of firms and sovereign wealth funds hold most of the upside, and the terms increasingly include compute commitments from the same investors writing the equity cheques. That circularity is worth watching closely.
Public money, slow but structural
Governments move at a different tempo. National compute programmes, the UK and US AI safety institutes, EU framework funding and chip subsidies collectively amount to billions rather than hundreds of billions. The influence is disproportionate, though, because public money sets standards, funds evaluations, and keeps a slice of the field independent of quarterly earnings.
What the Money Buys, Line by Line
- Compute. Multi-year contracts measured in gigawatts, not GPUs. Power is now the binding constraint more often than silicon.
- People. Senior research scientists at frontier labs command packages in the millions, often heavily weighted in equity that only pays out on a liquidity event.
- Data. Licensing deals with publishers and archives, plus thousands of expert contractors, doctors, lawyers and PhDs, paid $50 to $150 an hour to write and grade training material.
- Evaluation. Benchmark development, red-teaming and third-party audits, which remain a rounding error on the total but shape what labs can credibly claim.
- Energy. Power purchase agreements, gas turbines, and early-stage nuclear deals that only make sense on a ten-year horizon.
Notice what’s missing from that list: a lot of unglamorous science. Replication studies, negative results, small academic groups testing weird ideas on modest budgets. Those don’t scale into a press release.
The Underfunded Half: Safety, Evals and Independent Work
Estimates vary, but most surveys put spending on safety, alignment and evaluation at a low single-digit percentage of total AI research and development. That ratio has barely shifted despite years of public commitments. In practice it means the people deciding whether a system is safe to deploy are often working with fewer resources than the team that built it.
Academic researchers face a steeper problem. The best graduate students get hired away before they finish, and the compute needed to reproduce a frontier result is out of reach for most departments. Independent work survives on philanthropic money from a small set of foundations, which is a fragile arrangement for something this consequential.
There’s also a conceptual trap here. Much of what gets measured and funded is machine learning progress, and the distinction between machine learning as a toolbox and AGI as a destination matters when you’re deciding where the marginal dollar should go. Better benchmarks on a narrow task tell you almost nothing about generality.
Reading a Funding Story Without Getting Fooled
Announced capital is not deployed capital. A $40 billion round may be staged across years, and a chunk of it can come back to the investor as compute purchases. Valuations are paper. What matters is how much cash actually reaches a training cluster, and how many people are paid to think.
The same scepticism applies to technical claims made alongside funding news. This guide on telling a real AGI milestone from a marketing beat is useful when a raise and a breakthrough land in the same week, which they suspiciously often do.
Signals That Tell You More Than the Headline Number
If you want to track where AGI research funding is genuinely going, watch a few less glamorous indicators. Power procurement filings reveal the true scale of planned compute months before a launch. Hiring pages show which research directions have internal sponsorship. Open-weight releases hint at where capability is commoditising. And follow-on funding for evaluation outfits tells you whether anyone is serious about independent scrutiny.
Our running assessment of what actually moved in AGI progress in 2026 is a decent companion here, because the funding story and the technical story keep diverging. Capital has never been more available, and yet the areas where additional money would help most, evaluation, interpretability, and long-horizon reliability, remain the thinnest part of the field.
The most useful habit is to ask a simple question of any funding number: what does this let someone do next month that they couldn’t do last month? If the answer is “hire more salespeople” or “sign a bigger power contract,” that’s a business story. If it’s “run an experiment nobody has run before,” that’s research funding doing its job. The ongoing survey of AGI research news worth paying attention to is a good place to keep score.